As reported on November 18, 2026, Bitcoin miner MARA Holdings had disclosed sales of approximately 40,581 BTC for about $3 billion during the year. The shift was substantial: in 2024, MARA’s policy was to retain all the Bitcoin it mined and buy more when opportunities arose. It began allowing sales of newly mined coins in 2025, then expanded sales to its existing reserves in 2026.
The change does not mean MARA has abandoned Bitcoin holdings. It means the company is weighing those holdings against debt repayment, acquisitions and infrastructure spending. Its planned acquisition of Long Ridge Energy & Power shows how that choice works in practice.
From accumulation to sales
MARA held 44,893 BTC at the end of 2024. In that year’s fourth quarter, it bought 15,574 BTC with proceeds from convertible debt issuance. Its holdings rose to 53,822 BTC by the end of 2025, despite sales of approximately 4,076 BTC during that year.
Between March 4 and 25, 2026, MARA sold 15,133 BTC for about $1.1 billion. It then spent approximately $913 million to repurchase two series of zero-coupon convertible notes with roughly $1 billion in principal. That reduced outstanding principal and the potential dilution if the notes were converted into shares.
During the first nine months of 2026, MARA mined 6,916 BTC and sold approximately 26,984 BTC. Its holdings stood at 34,012 BTC at September’s end, down about 37% from the end of 2025. Of that balance, 14,752 BTC was freely available; the rest had been pledged or lent. MARA sold another approximately 13,597 BTC after the third quarter. For its financing decisions, total holdings and immediately available coins had become different measures.
The Long Ridge financing sequence
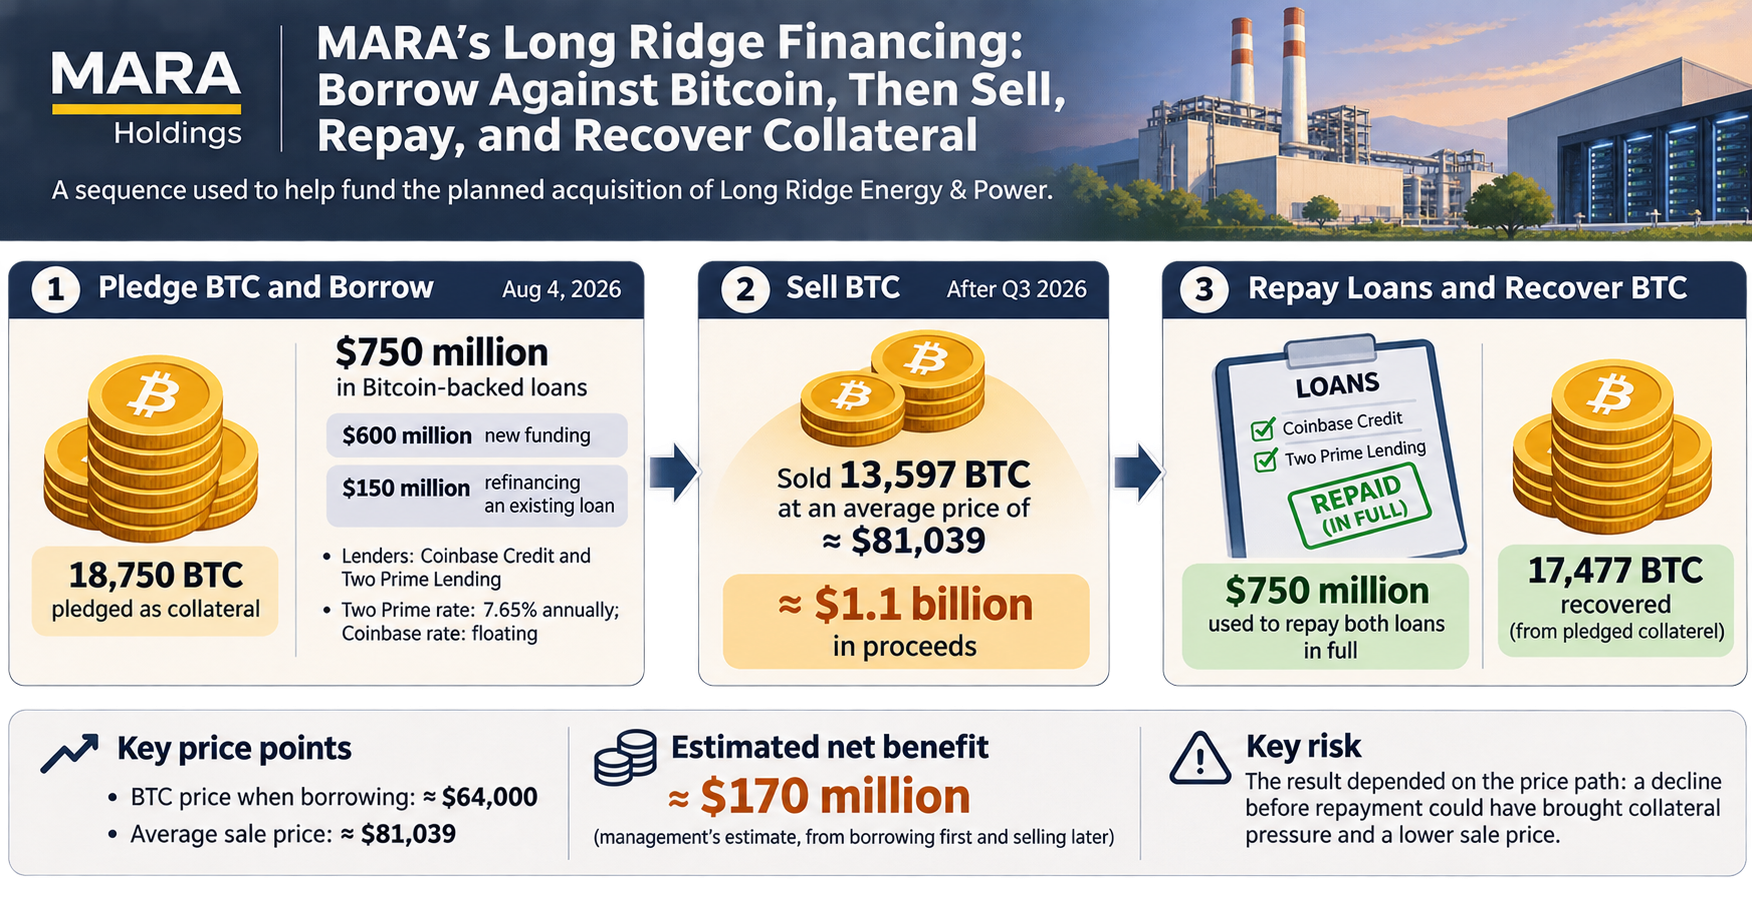
MARA announced in late April that it planned to acquire Long Ridge from FTAI Infrastructure. The transaction had an enterprise value of approximately $1.5 billion, including up to about $900 million in debt MARA expected to assume. To help fund the deal, MARA arranged $750 million in Bitcoin-backed loans with Coinbase Credit and Two Prime Lending on August 4. Of that amount, $600 million was new funding and $150 million refinanced an existing loan. MARA initially pledged 18,750 BTC.
MARA said Bitcoin traded at around $64,000 when it borrowed. Borrowing dollars against BTC let it retain the coins for a potential later sale rather than issue shares for this financing, but introduced interest costs and collateral risk. The Two Prime loan carried a 7.65% annual rate; the Coinbase loan had a floating rate. A sufficient decline in collateral value could have required MARA to post more collateral or take other contractually permitted steps, with pledged BTC at risk if it failed to do so.
After the third quarter, MARA sold 13,597 BTC at an average price of about $81,039, raising approximately $1.1 billion. It used $750 million to repay both loans in full and recovered the 17,477 BTC still pledged against them. Management estimated that borrowing first and selling later produced a net benefit of about $170 million. That result depended on the price path: a decline before repayment could instead have brought collateral pressure alongside a lower sale price.
The US Federal Energy Regulatory Commission approved the acquisition on November 4. When MARA reported results on November 9, it still expected closing within the following weeks. Repayment of MARA’s Bitcoin-backed acquisition loans was not repayment of Long Ridge’s existing debt, which was part of the acquisition terms.
What the acquisition could provide—and what remains uncertain
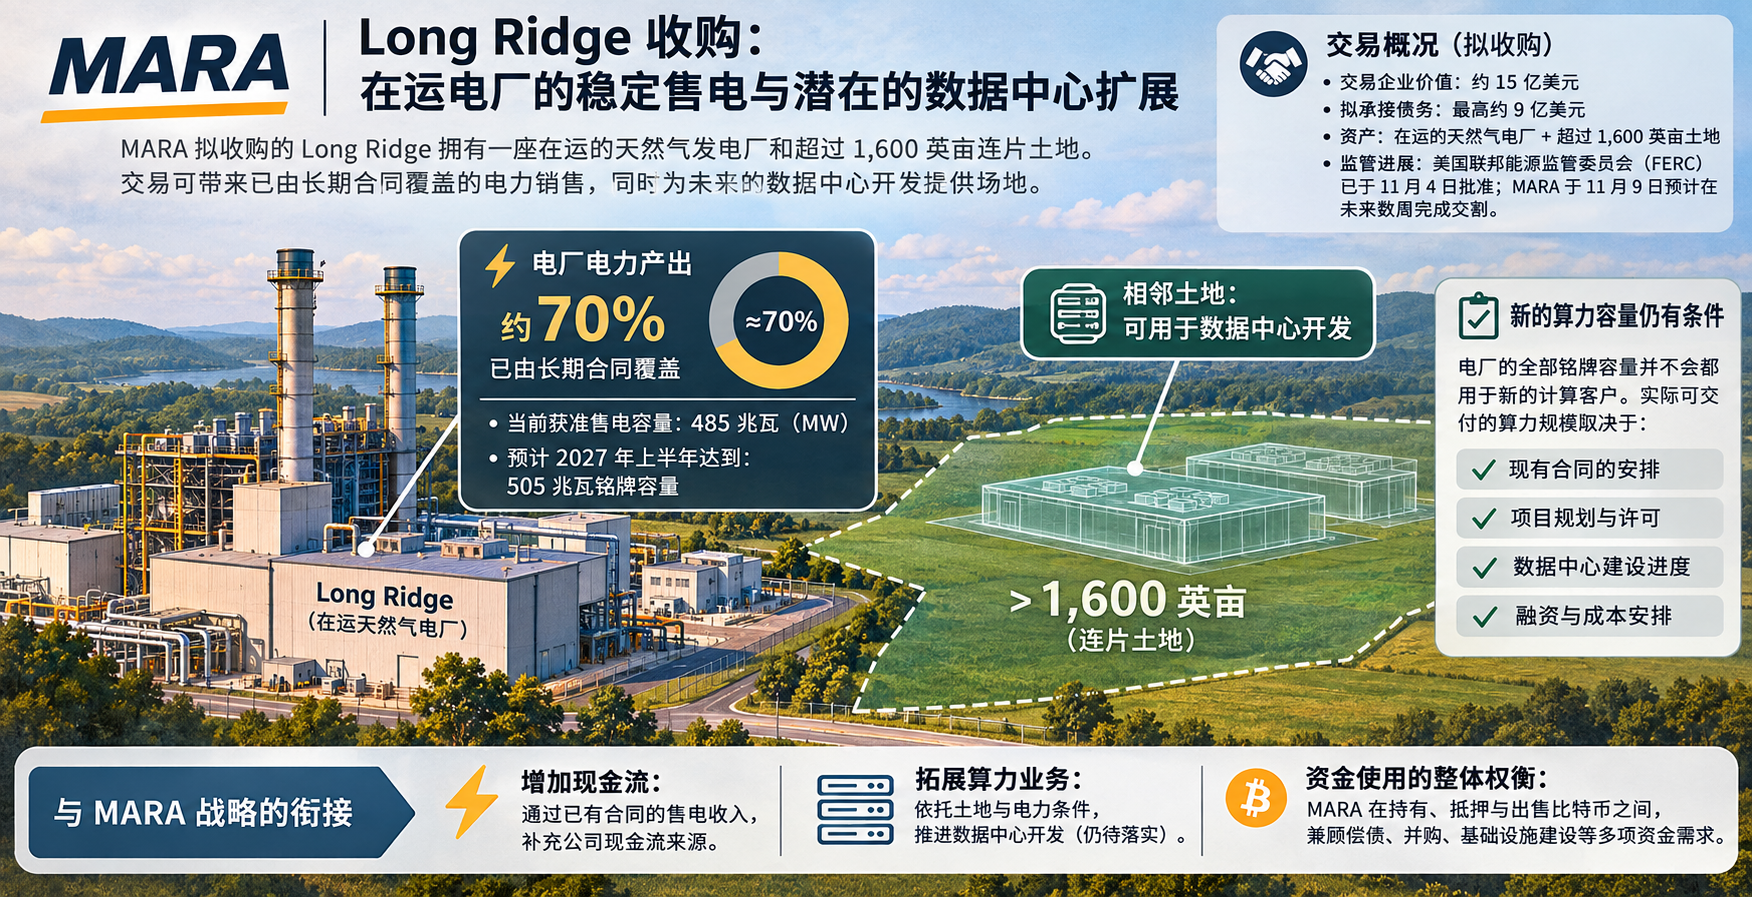
Long Ridge’s principal asset is an operating natural-gas power plant in Hannibal, Ohio, then authorized to sell 485 megawatts of electricity. MARA expected it to reach 505 megawatts of nameplate capacity in the first half of 2027. According to the company, long-term contracts covered roughly 70% of its output. The transaction also included more than 1,600 contiguous acres, while MARA already had an approximately 200-megawatt facility nearby.
If completed, the acquisition could add contracted electricity sales and a site for data-center development. It would not make the plant’s entire nameplate capacity available to new computing customers: existing contracts, project arrangements, permits, construction and financing all matter. Separately, MARA’s potential Texas development of up to 2 gigawatts remained subject to approvals, including grid connection. The company hoped to sign two data-center leases by the end of 2026 but said signing could slip into 2027.
MARA was also pursuing computing revenue directly. Its controlled subsidiary Exaion had signed a four-year, $79 million GPU computing-services contract with its first US customer. MARA’s stated pipeline of more than $3 billion in potential opportunities was not the same as binding orders.
The distinction between accounting gains and cash needs was visible in MARA’s third quarter. It mined 2,247 BTC, about 5% more than a year earlier, while revenue fell 35% to approximately $164 million. Net income of about $632 million included approximately $885 million in digital-asset fair-value gains. Such gains can lift reported earnings; construction, interest and acquisitions require cash.
On November 9, MARA’s board also authorized up to $500 million in share repurchases, without committing to a purchase schedule or amount. MARA identified AI infrastructure investment, convertible-note holders’ put rights exercisable from 2027, and possible buybacks as potential future uses of proceeds from Bitcoin sales. How much of its reserve it ultimately uses will depend in part on when new projects generate cash and how much funding they require before then.