In a report published on November 21, 2026, Fidelity Investments global macro director Jurrien Timmer said Bitcoin’s recent price performance had been poor and its correlation with the S&P 500 had risen markedly over the preceding weeks. In his view, its trading behavior looked more like that of a speculative risk asset than a monetary asset.
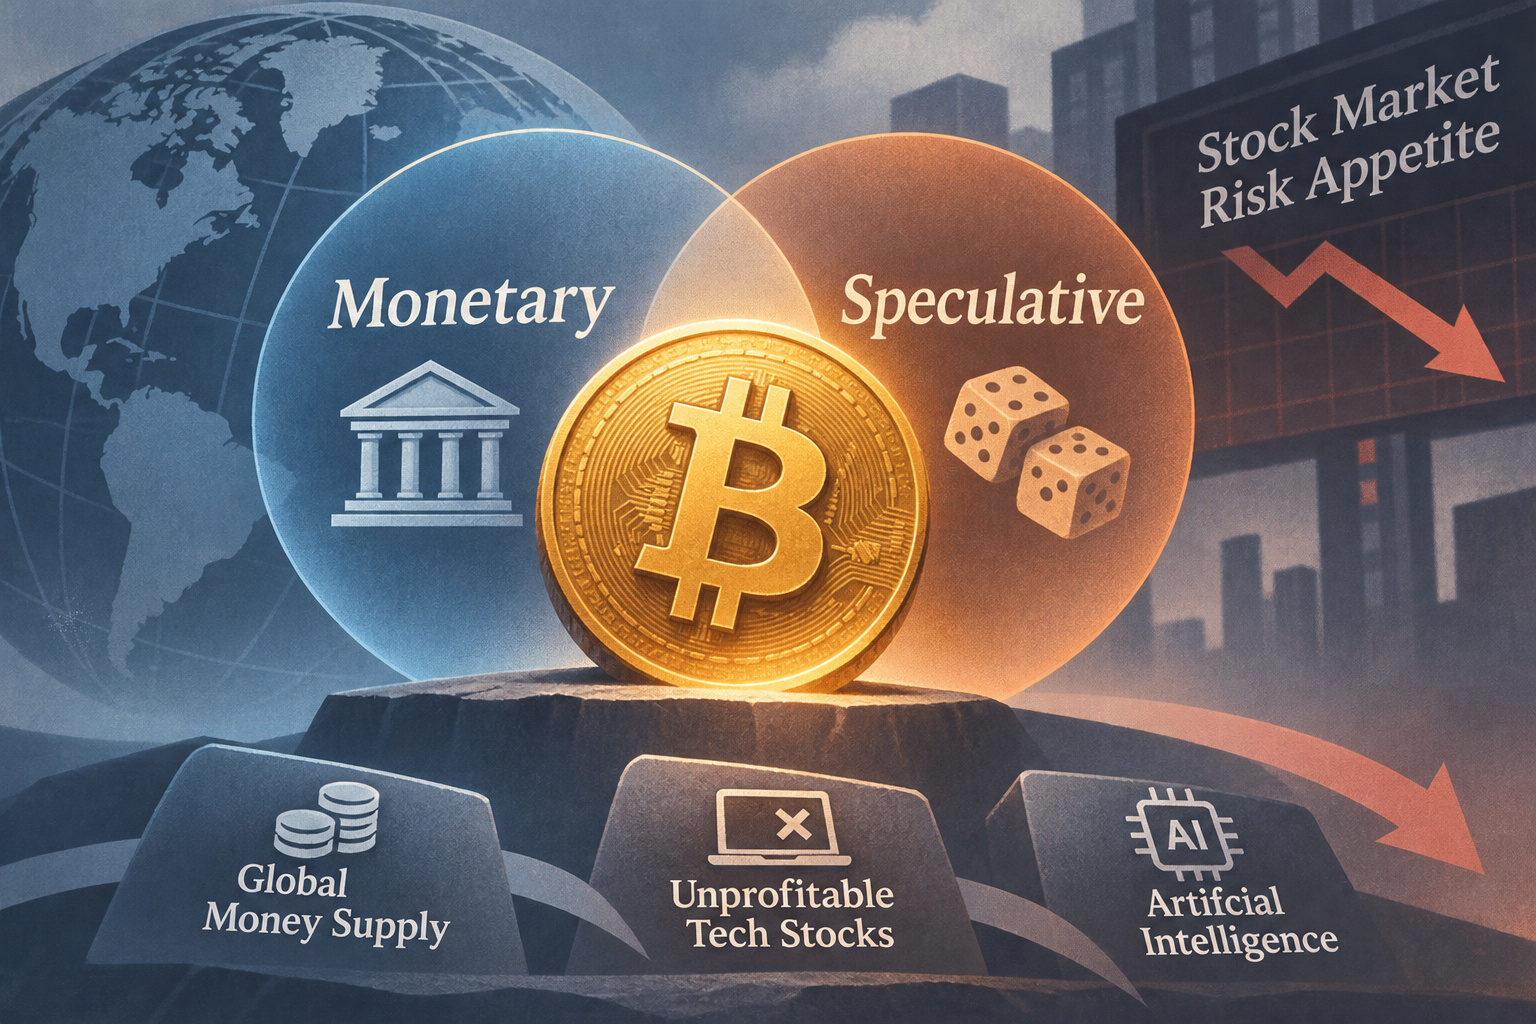
Timmer described Bitcoin as having both monetary and speculative components. He pointed to Goldman Sachs’ basket of unprofitable technology stocks and the rate of change in global money supply: when both expand rapidly, he said, Bitcoin tends to rise sharply, and the reverse also tends to hold. He said the artificial-intelligence theme was pulling back, risk appetite was weakening and global liquidity was declining.
That is Timmer’s assessment of the conditions at the time, not evidence that Bitcoin’s relationship with stocks or money supply is permanent. The distinction matters for a store-of-value claim: a monetary narrative does not, by itself, establish how an asset will behave during a period of falling risk appetite.